Thursday, October 13, 2011

POLITICAL ECONOMIC BRINKMANSHIP

After a sojourn to reflect and refocus on developments, what are the questions that dominate the political ether? The question I hear most often socially: "is the government (US or UK) doing the right thing?" My answer is a confident YES. Then I say "but both US and UK governments are failing to paint a clear picture of what they are doing and precisely why!"
see also: http://lloydsbankgroup.blogspot.com/)
Republicans in the USA and Conservatives in the UK are successfully twisting the issues to make recession and banking crisis appear domestic political failures. This is most telling for the UK's Labour government with a general election due in less than a year from now. But it has to be clear to intelligent observers that the UK's position is only to be expected and remains prudentially sensible as a proportionate set of responses to the crisis. PM Gordon Brown has maintained a stance that in effect says "trust me (us) to do the right thing to get us out of this crisis." The general public, at least the political chattering class, wants detailed explanations, not abstract assurances. The Conservative Opposition, echoed by the Liberals, have in the media created the axiomatic assumption that "public finances are in a mess." There is tremendous anger about banks and bankers, but the effect of ya-boo politics has been to divert anxious blame onto the government. Reading UK media the impression is gained that the UK's public finances and national debt must be the world's worst, if even no-one is quite sure what precisely defines concepts like 'finances in a mess'. Note the example of the following table. This reviews the financial debt of countries relative to GDP. There is a misnomer in the 3rd column (private sector debt) which is really household debt only as may be surmised in any case from column 7 of total bank assets (total loan gross exposures, not domestic only) given that public sector element is typically about half ratio to GDP with a few exceptions. There is a concerted forgetting that UK private sector gross debt over the past decade grew from 3 times public sector debt to 6 times public sector debt (3 times GDP) while, until the crisis broke, public sector debt held steady and fell slightly. Now the general public are being daily made anxious about the government fiscal deficit and medium term prospect of tax rate rises, most recently by the NIESR report on the economy, which fails to take account of the feedback effects of saving the financial sector. see the following: http://www.niesr.ac.uk/pdf/210709_225037.pdf
The NIESR has adapted the average recovery for previous recessions to state that incomes will not recover to the pre-crisis level (in real terms before unemployment rose and GDP experienced negative quarterly growth) until after 6 years. This is merely the average peak-to-peak period but has been exaggerated in the media as if a damning indictment of someone or something, similarly that GDP rates forecast are worse than the last published government figures (March Budget)? Yet, in fact there is nothing shocking or surprising about this. What is surprising is the NIESR's assumption that with a lower pound growth recovery will be export-led i.e. a total reversal of the credit boom growth previously! This assumption is conditional on whether government efforts to persuade or force banks to maintain or even increase lending will be effective, especially via the public sector owned banks. A very similar view would apply in the USA. What seems remarkably gauche about this outlook is that both UK and USA remain magnets for other countries foreign exchange surpluses. There is an improvement in growth expected for both insofar as the external account trade deficits will narrow as export-surpluses countries trade surpluses shrink, but this is not a recipe for halting unemployment rises. That depends on fiscal boosts and the banks cushioning the shrinkage of credit (deleveraging by banks to thereby most easily restore their capital ratios and by borrowers, especially households, cutting back their spending). Only restoring some credit boom effect and regaining confidence will slow and halt the domino, knock-on, rippling, or however anyone wants to describe it, negative vortex of beggar-my-neighbour impacts through the economy and all economies.
The banks have not woken up and smelled the coffee of their collective responsibility for economic recovery alongside government; they continue to live with pre-crisis mindsets, witness their inability and extreme unwillingness anyway, to tackle the bonus-culture. Government (UK and USA) have also not spelled out clearly enough what the banks are obliged by government to do to help both themselves and the economy. Lloyds Banking Group, for example, has improved its capital ratio to over 14% but mainly by reducing its risk weighted assets (loans) by nearly 40%, of which half was gained by an asset for BoE cheque swap with the Bank of England! The remaining half of the deleveraging is largely by retiring loans and not rolling them over. The effect of this alone in the case of but one bank has a 1% negative ratio to GDP and a GDP impact of possible minus 0.5%. Compounded by deleveraging by other major banks and we have a negative pro-cyclicality effect, precisely what banking regulation Basel II is most concerned to identify and avoid! Is the government forecasting or that of NIESR or any other model supposed to have predicted this? Governments created something of a cleft stick here, on the one hand wanting to see their financial interventions repaid soonest and on the other seeking assurances that the banks would maintain substantially more than minimum regulatory capital reserves and also maintain lending at pre-crisis levels. These objectives if not sensibly timed become mutually exclusive!
It is not hard therefore to conclude that what is less important right now is what caused the crisis and more important is what are the banks doing today? They are making the recession deeper. Bankers have an ready culprit they can blame for causing pro-cyclicality, the Basel II capital adequacy regulations, which ironically were designed with the objjective of addressing precisely this problem!
The banks still look at the underlying economy as exogenous to their business performance, not as something intrinsic that they can directly effect. They have as yet not embraced and understood Basel II Pillar II stress testing and economic scenario analysis and the central banks, government, and economic institutes like NIESR are not offering guidance and tools for how to analyse better the role of banks in the economy!
The banks are currently in a period of retrenchment, recoiling like scalded cats in the face of public sarcasm, and therefore unable to take responsibility alongside government in concerted efforts to redeem the economy. The public debate continues to confuse symptoms and underlying disease. The banking crisis may have had viral-like causes that transmitted throughout the whole financial system, but the public, led by politicians, media and pundits, continue to primarily blame all major banks as if they are individually guilty or heinous excessive risk-taking, even though the collective guilt is also obvious. Some pundits say we should have let individual banks fail absolutely as if diseased parts of the body-financial could be cut out to let the healthy parts prosper. This is myopic at best and ego-mania at worst, every cloud has silver linings for some whether short-sellers or doom-monger talking-heads.
Of course, what is it I'm saying here other than we need more comprehensive clarity delivered to the general public. How easy is that? Not easy at all. Opinions like politics are a market-place. After 2 years of the most intensive news coverage given to any crisis including war coverage, is the general public more attuned to detailed technicalities of what is happening and why, and what is being done, and what should be done, than before? Where can the public plant its feet and say this is real?
Timothy Geithner recently visited Alistair Darling but they failed to use the meeting adequately. They, both of their governments administration, need each other to validate each other's fiscal responses to the recession and financial interventions to salve the banking crisis. But, it is clear they don't quite get that. No one trusts bankers and only reluctantly trust economists. Politicians are generally mistrusted. Therefore this only leaves the inter-governmental sphere where mutual validation and confidence may be gained. My perception is that there is considerable confidence at this level, but it is not being communicated. In part this is because it lacks the tools for the job to analyse policy interventions sufficiently to know the timing of when to expect the positive benefits of policy measures to become apparent, by which I mean both finance sector interventions and budget fiscal deficits. The US and the UK are in recessions that are 6 and 4 quarters ahead of others, and consequently their fiscal deficits are higher and broadly in agreement. Politicians are sensibly wary of creating hostages to fortune, however, in making economic projections of qhen their actions should have positive results. This was a similar problem for central banks when trying to issue warnings ahead of the credit crunch, too wishy-washy elegantly shredded into lumpy bit kind of advice, with on the one hand and on the other etc. If there is one experience to be warned about I gained working in banks and as an economist is that too many people in key risk management positions are more risk adverse about their own careers than capable of setting this aside to state clearly what they believe. That said, it is doubtful that any major bank's board had it received cogent and accurate advice in say 2006 or early 2007 mapping out precisely what was about to hit them, would not have had 'shot' the bringer of bad tidings, at best had him or her dragged off to the funny farm. Economics is for various reasons, including bonus culture ones, something that most top bankers resist like the plague, whether qualified in banking or as is equally commonplace not educated about the totality of banking at all. Economics is sobering and not what inebriates can tolerate if given the choice? Perhaps polticians and central banks should take a leaf out of how wartime leaders such as Roosevelt and Churchill dealt with matters of public information and military command when they recognised that confidence mattered most combined with well-judged honesty in appealing to all to do their utmost in these difficult challenging times, etc? The recession and financial crisis is not a place for simply saying "I am your leader so trust me!" Time for more political courage, to step up and say that to the best of our judgment this is what we believe and deliver confidence-boosting expectations and take the political risk. The opposition political parties similarly need to be seen to stop playing party politics on the issue of getting out of recession and the credit crunch crisis. There are plenty of other matters they can be sarcastic about. Obama attempted in the US to gain a bi-partisan approach on the crises. he only half succeeded. In Europe, it seems to me that bi-partisanship has not even been proposed as a necessary or useful way forward! In the UK, Labour is pinning its hopes on being seen to have steered the economy through the recession. That has no precedents as a political strategy that I can recall. Better would be to simply go for honest statesmanship in the interests of what works best to restore public confidence in what it is that politicians are supposed to do best and most responsibly?
Geithner stated on 13th July that there is a good chance that the U.S. and other leading economies will start growing again over the next two quarters, but there are still significant risks to the outlook. This chimes with UK views (Government and NIESR) that there will be positive GDP growth in 4th quarter 2009. Essentially, this is based on narrowing of the external account and past recessions given that UK and US have both now reached the end of previous average recession periods, with one overlooked aspect that is that UK recovery tends to occur 2 quarters after the US, hence do not expect UK positive GDP before next year! Furthermore, both the official assurances of UK and US governments have been made without analysis of the cycle impacts of what the banks are doing. Their respective national economic models lack that depth; they cannot model for the details of the financial sector statistics within their GDP forecasting models!
Geithner said, "In my view there are still significant risks and challenges ahead," Geithner said when asked if he was concerned about the possibility of a double-dip recession. The issue is less double-dip in my view than simply 'double' given that the financial crisis is doubling the depth of what would have been a more normal to-be-expected recession. He said the world's major economies were largely in agreement on the steps that needed to be taken to boost economic activity. Yes indeed, but hard to guess that from statements by politicians except when speaking under the G8 and G20 umbrella. "I think we have remarkably strong consensus in place on core elements," Geithner said. This is not strictly true on the face of data, but is as good as it gets. He was speaking after talks with UK's Alistair Darling as part of a trip that will take in the Middle East and Paris. Geithner and Darling said leaders of industrialised nations would discuss the measures they are taking when the G20 meets in Pittsburgh in September. This is a critical month for the USA when its annual government budget ends and a new one has to be announced and voted through Congress. The number of state interventions in the banking crisis has slowed compared to last year. Everyone is treading water waiting to see what happens to banks balances by the end of the second quarter to then gauge what the US especially will decide it needs as a fiscal boost after September and in off-budget fiat (money market) interventions and command economy edicts to the banks. By then we should also have the measure of Quantitative Easing plus government bond auctions and we will probably be in the maelstrom of another nervous stcok market fall. Geithner will seek to reassure Gulf Arab states this week that U.S. dollar assets they hold in large quantities remain a strong investment. This is bolstered by scare stories about the Euro trillions of toxic debt in the Eurozone. On the one hand a strengthened dollar and weaker Euro should add to containment on oil prices on top of fall in demand, on the other hand there is a strong motive by foreign investors to anticipate another dip in US equity and asset values. A recent decline in Saudi foreign assets shows the purchase of U.S. Treasuries by Washington's Gulf allies, five having currencies pegged to the dollar, at levels seen in the past decades should no longer be taken for granted. This reflects narrowing of the US external account, hoiwever, and is not worrisome since the US, like the UK, now want their government bond new issues to be bought by domestic buyers, principally by the banks. The banks may foolishly insist on quid pro quo: "we'll buy your debt if you lessen the pressure on us to maintain lending levels and let us deleverage further!" Negative growth pro-cyclicality by banks has some way yet to run. If we take our best bets on this from past recessions, expect the banks to continue shrinking their household and corporate loan books at least up to the 3rd quarter of 2010!

Wednesday, April 20, 2011

Property lending and rules to save banks from themselves

Millions are frustrated because banks wll not lend them money to buy or develop property. Banks ascribe their lending restrictions to the new "Basel III" capital requirements (effective in 2012). This is not strictly a valid reason. Borrowers and others are given such simple reasons because the total picture is fraught with difficulties in striking the right balance between opposing demands, dogs and fire hydrants, rock and hard place etc. What is going on, or not?
Banks are shrinking their balance sheets and that inevitably means property lending (70% of UK and USA banks' customer loans - after exclusing loans to rest of finance sector which are also shrinking) and also hoping desperately to sell on bundles of property loans and foreclosed properties, if only they can find long term deep pockets to sell to without too steep a discount.
The retreat by banks from property is one reason why insurers and other institutional investors are getting into property lending, seeing an opportunity to do so without competition from banks and expecting higher returns than the banks can achieve.
The bankerspeak financial technicalities.
Basel III changes to higher capital reserves and more core capital of banks (higher amounts and higher loss-absorbing quality) are not genuine reasons for reducing the general loan exposure - it is really about narrowing the funding gap (between deposits & loans) that is filled by selling Medium Term Notes into the "wholesale interbank funding market" and banks are each fearful of when they next have to go to market to replace their MTNs on maturity (big amounts periodically every 3,6, 12, 18 months etc.).
"Internally generated capital" is recovery of monies loaned plus net interest income and other realised profits, and the banks are torn between using those gains to reduce their funding gaps or to increase their capital and liquidity reserves (as regulators under the name of "Basel III" require). They are also torn about how much they can allocate to bonuses rather than dividends. Hence, the banks blame Basel III for lower lending and want everyone to know that as part of their pressure on regulators and governments to soften or postpone Basel III and even on shareholders re. dividends and government and other pref bond holders to expect lower % coupons for longer - when actually it is really about narrowing their exposure to wholesale lenders i.e. to severely reduce their funding gaps, which UK banks have already halved from £1 trillion to £500bn, and falling, and that is a lot of balance sheet liquidated and internal capital generated.
The banks know the wholesale funders well and what is looked for an expected because they are also such funders in terms of their large loan exposures to other financial sector borrowers and have been liquidating cross-border interbank loans dramatically.
When (how soon) a bank has to next replace/refresh its "funding gap" finance will dictate its current openness to agreeing new loans; they are keen to say to their funders here is £5bn matured MTN repaid to you and we only want you to roll-over and buy £2.5bn of new MTNs back from us, which is supposed to sound good to the lenders and there should therefore be minimum fuss or embarassment (narrower spreads) that could leak out to market and damage the share price.
Property (development especially) is seen as riskier, and in addition UK banks are being warned by regulators to reduce the concentration of risk they hold in this one sector (property), especially while they are holding large amounts of receovered property collateral and seeking to sell on about 20% of their property loans (i.e. £260bn), probably with 15% haircuts = £40bn, some % of which could appear as paper loss relative to the outstanding loans, interest & charges that relate to the collateral recovered, perhaps £5-10bn (a wild guess).
The banks are in a bind partly of their own making insofar as the property market (asset prices) cannot recover until new property lending grows and yet until there is recovery they cannot sell their property exposures without risk of substantial loss, and without clearing out of a lot of property they cannot resume property lending.Therefore, if institutional investors (who are the major shareholders in bank other than governments) step in to make up the shortage in new property lending this, if on a large enough scale, could be important to breaking the logjam, and should be profitable to institutions in two ways (for themselves directly and via improved balance sheets of the banks), and given that property conditions are a major aspect of economic growth recovery.
But, when property lending is resumed by banks more assiduously the first port of call may be to refinance troubled loans rather than agree new loans to new borrowers, that is long term loans especially, while short term lending only looks relatively attractive to many banks. Medium to long term lending appears to have too many uncertainties i.e. the risks are very hard for them to compute.
The wider context includes policy that is torn between being seen to put in place measures that can be claimed to make sure the credit crunch recession never re-occurs, while also needing bank lending to stop shrinking and then to grow to generate more certainty of substantially higher economic growth. This facing in contradictory directions is why there is much fudging about the impoact of Basel III regulation including the Vickers Commmission recommendations that many outside UK as well as in UK hoped would provide a clear new line to follow and refresh the impetus of the G20 agenda of about 100 adjustments, policies and new institutions to protect the financial system from itself.
So-called "Basel III" rulings aim to increase banks’ tier 1 capital base from 2% to 4.5% (ratio to gross loans, or twice this to risk adjusted loans) to improve the resilience of banks. These discourage securitisation transactions, and there are four ways banks can increase their capital base to meet new ratios: raise more long term capital themselves (internally generated by cutting costs, bonuses, dividends and coupons), raise more in deposits, shrink loan balance sheets, commit less own capital to investment banking (market trading & derivatives), and reduce exposure (in economies where property dominates) to property and property loans.
There is the hope that interbank lending and funding gap finance and securitisation of loanbooks will sooner than later return as a reliable and substantial option, but only once the banks look safer bets i.e. the banks are strong enough to again dictate the loan spreads to those they borrow from. That is unlikely so long as the sovereign debt crisis reflects badly on banks and so long as Basel III looks hard for banks to comply with, even if these are very much parts of the banks own PR to shift the blame (playing up the sovereign debt crisis) and to soften new capital rules (foot-dragging on Basel III).
From the point of view of individual borrowers going to the banks with wonderful schemes of great quality all this bigger picture about future impacts reasons given for refusing loans is an immense frustration. It is actually the excat inverse of the pre-credit crunch past when banks ignored the bigger macro-economic and regulatory picture and approved any loans that passed merely microeconomic tests based on past high growth experience and not on forecasting future downturns. Yet, while the medium term future should be one of renewed growth and recovery, Basel III is ensuring future risks are assessed in terms of possible repeat of economic down turn (double-dip or another recession)!
In the case of seeking loans from banks that are underwritten or otherwise backed by government should ensure that banks can lend comfortably because the risk is low. But, low risk also means low net interest income when banks are anxious to raise their % net interest income, and given uncertainties about even government finance (subject to unexpected renewed cost-cutting at budget time) state-support may not of itself be sufficient to get the banks to lend. Institutional investors seeking to fill the gap also may not be attracted sufficiently by the low margins despite state guarantees. They are attracted by commercial property, not residential, and are not stepping into property lending because they are attracted by low margins of bank lending. Insurers are attracted by the higher interest income generated by commercial property loans compared with government bonds.
Over half a £/€trillion in commercial property loans are maturing in C.Europe over next 3 years and possibly a third of that additionally in the UK. Institutional investors will step in where banks fail to roll over what is of good quality and cannot be all repaid, and are already now financing about one quarter of comemrcial property lending.

Saturday, November 20, 2010

Accounting principle- Accrual Basis

 Figures generated / kept in accordance to accounting principle is prepared on accrual basis. For instance, accountant record the provision for warranty ( based on estimate) even though there's no actual cash/ economic outflow yet.

In finance, cash basis figures are more relatively more valuable , as compared to accrual basis ( advocated by accounting principle), in order to value a business.

What do you think ? You prefer a an accrual method or cash method in valuing a business?

Auditing Creditors- Creditor Turnover Analysis

 In audit, it's essential to form an expectation of the Company's results before we really drill into the details. We compare the actual Company's results to our expectation, and investigate the variances accordingly. This is the analytical procedures adopted by most of the audit Company. Besides, we also compare the result / financial position with prior period.

Creditors' turnover anlaysis is one of the auditing procedure we performed. What are we expecting from the audit client, in general. We expect the creditors turnover (days) to increase, as compared to prior period.

To illustrate, majority of our audit clients are affected by the economy turmoil. They are squeezing suppliers' credit ( by delyaing the repayment), in order to maintain the Company's working capital, as our audit client's working capital are most likely affected by the delay of repayment from customers.

We have formed an expectation, and we will compare the actual result with our expectation. Any unusual movements need to be identified.

Auditing: Annual Budget vs Actual Results

 Company prepare budget and use budget as a performance benchmark and monitoring tools. For instance, senior management can question sales department if their actual yeat-to-date entertainment has exceeded the budget before the end of the year. Budget is , usually, prepared and approved at the beginning of the year or before that.

Budget has incorporated management's forecast, estimation and outlook of the business in the coming times.

Is management's budget useful to auditor?

The answer is yes. Budget, which represents management's expectation, should be compared against the actual results. Significant variances should be investigated. Apparently, management would have to explain the variances. It's important for auditor to find out the reason of the variances to identify potential changes in business operation, significant developments during the year.

Understanding how management view the business (by looking at the budget) is a crucial stage in audit planning, it enhance our knowledge and understanding on the business, the industry and the overall economy as a whole.

Disposing capital-intensive business


What's happening in the corporate world now?

Capital-intensive require heavy investment of resources, including, but not limimted to: cash, human resource,management's effort, etc. As part of the restructuring exercise to scale down, there are evidence that a lot of corporate are disposing off capital-intensive business.

How would disposing capital-intensive business benefit the corporate?

- immediate liquidity ( i.e. proceeds from disposal)
- better working capital management
- allow management to evaluate other business opportunities
- lesser resources are required, which allow the business to scale down
- higher return on asset ("ROA") ratio

However, it's always not easy to dispose off a capital-intensive business unit/ busines during this business environment, unless a substantial discount is given to the potential buyers.

Accounting treatment for tax penalty


One of our Accounting & Audiitng blog reader inquired us the following:

" How should penalty on late repayment for tax been accounted for?"

Should it be a tax expense? Should it be other expenses?

To clarify: penalty imposed by inland revenue authority on late repayment for tax should not be accounted for as tax expense; it should be accounted for as administrative expense/ other expense.

No depreciation charge on asset held for sale

This is to confirm that if a property is classified as asset held for sale, no depreciation is to be recorded.

To illustrate, Company ABC entered into Sales & Purchase agreement with 3rd party to dispose one of its property. The Sales & Purchase agreement may take months to complete. In this instance, Company ABC re-classified the property from Property, Plant & Equipment to Asset held for Sale upon entering the Sales & Purchase agreement.

Asset held for sale is de-recognised from the balance sheet upon the completion of the Sales & Purchase agreement.

Auditing Creditors

One of the procedures required to audit trade creditors account is to audit the creditors' statement received from the audit client's suppliers (i.e. external audit evidence).

In normal business circumstances, suppliers will send their monthly Statement of Account to their customers to inform the customers in relation to the outstanding balances. Hence, our audit client will , most likely, receive statement of account from the suppliers.

As part of audit procedure, we can check the suppliers' statement (received by our audit customers) against the creditors' balance recorded in their book. Discrepancies need to be investigated. Statement of account served as an external confirmation to check if our audit client's book has been prepared properly.

However, there are suppliers who do not have practices of sending out Statement of Account to their customers. In this instance, we can send external audit confirmation to the suppliers to confirm outstanding balances.

Cash audit- internal controls in cash process- cash payment

In our earlies entries in relation to cash audit, we discussed about the audit procedures of auditing unpresented cheques. We will discuss more extensively for audit procedures in auditing cash and bank balances of our audit clients.

Auditors may consider test the internal controls of the client's cash process. For this entry, we will provide an overview of the possible audit procedures to test the internal controls in cash payment process:

(a) select certain number of random samples, and test that payment voucher are properly prepared and authorised

(b) select certain number of random samples, and test that bank reconciliations are properly prepared and reviewed

(c) select certain number of random samples, and test that journal entries are properly posted into General Ledger

(d) select certain number of random samples, and test that payment voucher details match with the corresponding payment details

Thursday, November 11, 2010

The Types Of Accounting

Accounting is the art of analyzing and interpreting data. It may not be apparent to some but every business and every individual uses accounting in some form. An individual may knowingly or unknowingly use accounting when he evaluates his financial information and relays the results to others. Accounting is an indispensable tool in any business, may it be small or multi-national.
The term "accounting" covers many different types of accounting on the basis of the group or groups served. The following are the types of accounting.
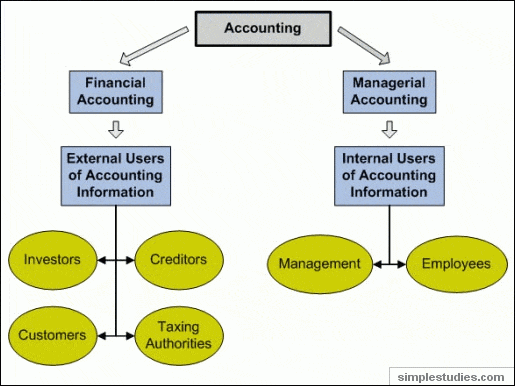
1. Private or Industrial Accounting: This type of accounting refers to accounting activity that is limited only to a single firm. A private accountant provides his skills and services to a single employer and receives salary on an employer-employee basis. The term private is applied to the accountant and the accounting service he renders. The term is used when an employer-employee type of relationship exists even though the employer is some case is a public corporation.
2. Public Accounting: Public accounting refers to the accounting service offered by a public accountant to the general public. When a practitioner-client relationship exists, the accountant is referred to as a public accountant. Public accounting is considered to be more professional than private accounting. Both certified and non certified public accountants can provide public accounting services. Certified accountants can be single practitioners or by partnership ranging in size from two to hundreds of members. The scope of these accounting firms can include local, national and international clientele.
3. Governmental Accounting: Governmental accounting refers to accounting for a branch or unit of government at any level, may it be federal, state, or local. Governmental accounting is very similar to conventional accounting methods. Both the governmental and conventional accounting methods use the double-entry system of accounting and journals and ledgers. The object of government accounting units is to give service rather than make profits. Since profit motive cannot be used as a measure of efficiency in government units, other control measures must be developed. To enhance control, special funds accounting is used. Governmental units can use the services of both private and public accountant just as any business entity.
4. Fiduciary Accounting: Fiduciary accounting lies in the notion of trust. This type of accounting is done by a trustee, administrator, executor, or anyone in a position of trust. His work is to keep the records and prepares the reports. This may be authorized by or under the jurisdiction of a court of law. The fiduciary accountant should seek out and control all property subject to the estate or trust. The concept of proprietorship that is common in the usual types of accounting is non-existent or greatly modified in fiduciary accounting.
5. National Income Accounting: National income accounting uses the economic or social concept in establishing accounting rather than the usual business entity concept. The national income accounting is responsible in providing the public an estimate of the nation's annual purchasing power. The GNP or the gross national product is a related term, which refers to the total market value of all the goods and services produced by a country within a given period of time, usually a calendar year.

Pursuing a Career in Accounting? Opportunities Are Yours For the Taking


If you're interested in pursuing a career in accounting or auditing, the opportunities may be yours for the taking. According to the Bureau of Labor Statistics' Occupational Outlook Handbook, 2008-09 Edition, the accounting profession will experience strong job growth over the period from 2006 to 2016. Accounting jobs are expected to grow by 18 percent between 2006 and 2016. This growth is faster than the average for all occupations. It is projected that almost 226,000 accounting jobs will be created during the ten year period. The strong growth in accounting and auditing jobs is expected to result from economic expansion, changes to financial laws, and stricter corporate governance. Accounting career opportunities will also be created by changes to financial reporting standards, business investments, mergers and acquisitions, and other events that are expected to lead to greater scrutiny of accounting practices and company finances. Growth in accounting jobs will also be driven by the desire to make government agencies more accountable. According to the Handbook, candidates with a master's degree, who obtain certification or licensure, or who are skilled at using accounting and auditing computer software will have the best career opportunities.
What jobs do accountants and auditors do? The role of accountants and auditors is quite broad. Generally speaking, accountants and auditors prepare, analyze, verify and communicate financial information for clients that may include corporations, governments, non-profit organizations, or individuals. But the specific job descriptions of accountants and auditors vary depending on the type of accounting and auditing job.
What types of accounting career opportunities are there? There are four major fields of accounting and auditing: public, management, government accounting, and internal auditing.
Public accounting jobs: Public Accountants provide a wide range of consulting services relating to accounting, auditing, tax, and other financial activities. A career in a public accounting involves providing services such giving advice to companies or individuals to help them get certain tax advantages and preparing and filing income tax returns. External auditors are responsible for auditing financial statements for companies to ensure that they have been prepared properly. Many public accountants have the professional designation Certified Public Accountant (CPA) and they may work on their own or in public accounting firms.
Management accounting jobs: Management accountants prepare and analyze the financial information of the companies for which they work. If you pursued a career in management accounting, you would be responsible for maintaining budgets, managing expenses, analyzing financial information, preparing financial reports and managing company assets.
Government accounting jobs: A career in government accounting means you would be employed by a Federal, State, or local government agency. Government accountants are responsible for maintaining and analyzing the financial records of these agencies. They may also be responsible for auditing private businesses and individuals. For example, accountants for the Internal Revenue Service are employed by the federal government to review taxes received by businesses and individuals. In addition, they are tasked with the responsibility of ensuring that the various government agencies are making expenditures in accordance with applicable laws and regulations.
Internal auditing jobs: Internal auditors are responsible for ensuring that the financial records of a company or individual are accurate. They check for fraud or non-compliance with laws, and they help to prevent financial loss. Other responsibilities of an internal auditor may include reporting on audits, advising on or recommending changes to a company's operations an/or financial activities, reviewing data regarding a company's assets, liabilities, stock, income and expenditures, preparing reports and financial statements, and reviewing compliance with corporate policies and government regulations.
What are the educational requirements for a career in accounting or auditing? Your duties as an accountant will vary according to what type of accounting you decide to specialize in or what kind of accounting job you want to pursue. Accordingly, if you are pursuing career opportunities in accounting or auditing, the education and training requirements can vary depending on your role. Most accounting jobs require at least a bachelor's degree in accounting or a related field but some employers will only consider job applicants with a master's degree in accounting, or a master's degree in business administration with a concentration in accounting.
Licensure and certification for accounting jobs: Only a Certified Public Accountant is permitted to file reports with the Securities and Exchange Commission (SEC). Accordingly, if you're interested in a career working for a public company that's registered with the SEC, you need to be licensed as a CPA by your State Board of Accountancy. Most States require CPA candidates to be college graduates and to have some accounting experience. To become a CPA, you must pass a four-part examination prepared by the American Institute of Certified Public Accountants (AICPA). This is required by all States.
Things that can help increase your accounting career opportunities:
o Previous experience in accounting or auditing, such as experience gained in summer or part-time internship programs, will help your chances of getting an accounting job.
o Knowledge of computers and financial software applications will make you a stronger candidate for an accounting job.
What skills do you need to succeed in an accounting career? If you're interested in accounting career opportunities, you must:
o be proficient in math and you must have excellent analytical skills
o communicate effectively
o be good at working with people
o have basic accounting knowledge
o be familiar with accounting software
If you're seriously thinking about accounting or auditing career opportunities, information is available from the following organizations:
o AACSB International
o American Institute of Certified Public Accountants
o National Association of State Boards of Accountancy
o Institute of Management Accountants
o Accreditation Council for Accountancy and Taxation
o The Institute of Internal Auditors
o ISACA
o Association of Government Accountants

Should I Practice Public Or Private Accounting


Bachelor of Science in Accountancy is one of the picked courses among college students. Many have chosen this field of study because it has a wide scope of availability in terms of future stable job with attach high rate of pay. Career opportunities in this course have two categories and these are Public and Private Accounting.
Professionals who worked for a particular Accounting Firm and worked for several clients are called Public Accountants. These kind of firms employ thousands of accountants because their services are offered from one-person operations to multinational organizations. Audit or tax is two paths where in a Public accountant is going to be. Auditors as you called for those in the audit practice strictly and carefully audit financial records and business transactions of a client. Accounting records that are reported by the companies are ensured by the auditors that those documents accurately abide with national accounting standards. Professionals who are in the tax practice provide services similar with that of an auditor but with a more focus specialization. Professionals who handles tax ensures that clients tax record are well documented and do follow the guidelines established by government taxing policies. Another role of a tax accountant is to help minimize the tax liability of a client.
On the other hand Private Accounting is more concern with internal accounting. This internal accounting is the accounting functions of the company. Corporate Accountants which is another name for private accountant performs the same duties as the Public accountant but this task are limited towards the companies that they are employed.
The distinction between Public and private Accounting is that Public is more involved with collecting external financial information's while Private is much inclined with the use of internal information's to aid managers in giving effective decisions.

Questions and Answers About Starting an Accounting Career


An accountant plays a very important role in the functioning and efficiency of a corporation. They provide a number of vital business services to clients including the management of financial matters, auditing, and handling tax issues. However, the specific duties performed in an accounting career will differ depending on what field the practitioner works in, be it public accounting, management accounting, government accounting, or internal auditing.
Accountants will generally use computers and special accounting programs to assist them in their duties. Accountants can summarize and organize data in particular formats to make them more suitable for storage or analysis. The programs also remove a lot of the tedious manual work of accounting out of the job. For this reason, accountants will generally have a very high level of competence with computers and many employers will require them to be proficient in these programs to help keep their work accurate.
The environment in which an accountant works will generally vary depending on what field of accounting he/she is in as well as what type of company or organization he/she works for. The vast majority of accountants work in an office setting, often with many other coworkers and colleagues; although, some accountants are self-employed and may be able to work part of their job at home as well. Most accountants work a standard 40-hour week; though, there are exceptions especially in the case of tax specialists and self-employed accountants who may work longer hours during certain times of the year.
Public accounting firms often send their accountants to their clients' place of work or residence to perform audits. In this scenario, there can also be a lot of traveling involved. Accountants who travel often will most likely use a laptop to allow for the increased mobility of their accounting programs, data, and other information needed on the job.
Accountants, regardless of their chosen field, require a proficiency in mathematics as well as business. Many accountants are unlicensed, especially in the fields of government accounting, management accounting, and internal auditing. A bachelor's degree in accounting or a related field is required to become licensed as a Certified Public Accountant (CPA), Public Accountant (PA), Registered Public Accountant (RPA), or Accounting Practitioner (AP). Some companies will require their accountants to hold master's degrees as well.
There is a large demand for accountants, and as more businesses are created in the coming years, the demand is expected to increase. The rapid expansion of business is also expected to have a large effect on the types of responsibilities accountants will have. Nevertheless, these jobs can be very competitive, and many businesses are increasing their standards by which they hire and the qualifications they demand.
Accountants who have a great knowledge of computers and many different accounting software will have a better change of employment. Also, those who have more education, training, and experience will also have an edge in the job market. It is also important for accountants to demonstrate interpersonal skills as this will also help them perform their job more effectively and get along better with clients.

Monday, September 27, 2010

Banks and Basel III: blackmail or chainmail?

Will the various new so-called “Basel III” rules make the world safer from financial crises? There should not be a short answer to such a complex question – but my answer is yes, and no, not much either way, and, looking back, taking the metaphor of New Orleans sea defences and levees, higher equity in banks core capital reserves means the same as adding only inches to the height of ‘sea defences’. Protecting the financial system is a systemic challenge; individual breaches in flood defenses may be contained or lead to general failure.
Erecting barriers, by setting global prudential standards, to prevent calamity is the job of the Basel Committee on Banking Supervision (BCBS), to mitigate, prevent or postpone, another Credit Crunch, its job is to agree techniques, laws, rules and guidelines to resist a 1/25 tidal surge or the 1/100 that some say defined the Credit Crunch.
But, what do we think of bankers’ response to new safety rules? They sound like road drivers opposing lower speed limits.
The banks publicly resent being told to increase reserve ratios. It is the same reaction if government asked the private sector to build and pay for sea defenses. The banks’ lobbyists such as the BBA and IIF warn gloomily of a probable £1 trillion less lending in the UK alone over the next decade - maybe €7 trillion less lending across the EU.
Our inglorious banks have, it seems, regained a bold-faced confidence sufficiently to complain loudly about new prudential rules, as if these ingrates* have superior information to warn us not to kill the Golden Goose**, and as if everyone else will trust that judgement and believe the banks?
But, is it realistic to suppose that excessive fear of another financial crisis and mistrust of banks by regulators and taxpayers could lead to borrowers and the economy paying a big penalty for higher equity-capital reserve ratios?
Alongside the new capital rules, the Basel Committee also published two papers on economic impact that media commentators and banks’ lobbyists, appear not to have read? These assessments are more sanguine and define it as a (very) “conservative” view to assume all the impact of Basel III will be borne by higher customer borrowing costs and reduced lending.
The Committee agreed higher equity capital ratios (announced 12th September) to oblige banks to hold more to absorb the inevitable losses of a recession. The changes are intended to mitigate and or postpone the next “financial crisis”. More equity means shareholders will bear the losses, as they have done so already in the Credit Crunch?
Reserves are ratios to loans and investments net of collateral after risk adjustments. New rules require twice as much equity reserve as before, but with years to get there, by when the USA and UK will probably be in recession again? Higher “capital buffers” are also imposed, but only in the proportions that national supervisory regulators are already demanding.
Bankers’ bleat that capital hikes mean higher customer costs, less lending, and will only jeopardize recovery. But, by the time the ratios kick in we’ll be past recovery and into the next boom. Bankers, it seems, don’t want us to see the many ways they can generate more “own capital”, including via higher profit-retention and paying smaller bonuses!
The BIS paper on macro-impacts finds that for each 1% increase in the capital ratio loan costs could maximally rise by 13bp, and for every 1% higher liquidity reserves loan margins rise 25bp, assuming RWA is unchanged. This falls to 14bp or less if RWA falls by shifting the risk diversity to less risky assets without any fall in gross assets. If banks adjust their expected return on equity from 15% to 10%, then each 1% increase in capital ratio is recovered by a 7bp rise in loan margin, well within what can also be achieved by cost-cutting or other relatively painless measures.
BIS is very clear: “Banks have various options to adjust to changes in required capital and liquidity requirements other than increasing loan rates, including by reducing ROE, reducing operating expenses and increasing non-interest sources of income. Each of them could cut the costs of meeting the requirements. For example, on average across countries, a 4% reduction in operating expenses, or a 2 % fall in ROE, is sufficient to absorb a 1% increase in the capital/RWA ratio. In practice, banks are likely to follow a combination of strategies.”
Cost of borrowing by banks should reflect the riskiness of banks. If banks are safer because of new rules then the risk spread banks pay to borrow should fall. But, if bankers don’t rediscover prudence, alongside a humbler piece of the pie, as governments anxious to balance their budgets exit from bank-aid measures, then the banks will have to pay more to borrow funding gap finance and to attract and retain deposits.
Let’s not forget that the Credit Crunch was caused by funding gap finance cost (risk spreads) becoming uneconomic, too high to ensure positive corporate lending margins. Why, because banks lost credibility and it is not at all clear that they can presume to have that back now, not while ratings agencies keep so many banks on the bottom-most rungs of unsecured credit grades.
The rates borrowers are charged should be dictated more in future by competition and demand than by banks seeking again the super profits of the years before 2008, and in Europe especially if cross-border lending is to recover and grow? Banks may accommodate higher reserve ratios by requiring more collateral and by exercising other risk mitigations including diversifying better across all economic sectors and by changed business models. Banks in trade-deficit countries are biased to property lending and in export-surplus countries to industrial trade.
In the years up to 2007, banks grew faster than underlying economies, earning dispro-portionately high profits, 25% - 50% of all profits of publicly quoted companies, which should be unsustainable. Shouldn’t they adjust to more realistic or reasonable profit targets?
The new rules are a cornerstone of the G20 response, a global effort to ensure stable international banking. The rules redefine “core tier one capital”, a measure of a bank’s solvency, plus sufficient liquidity to survive a short-run crisis with less dependence on short-term borrowing. The new ratios would not have saved the banks that crashed in the credit crunch but are a step in that direction to take some pressure off future government budgets.
Dame Angela Knight, chief executive and spokesperson of the BBA, was almost entirely negative about the announcements. She warned that banks have no choice except higher loan margins that will “suck money out of the economy” – by which she means the non-financial economy - as if banks’ profits, bonuses, and speculation can’t do that already. German banks made similar objections, and others too.
Three major UK banks have threatened to domicile themselves elsewhere if the UK government and its Banking Commission decide to split retail from investment banking - Paris and Frankfurt are offering lower tax to induce UK banks to move! Is this further evidence of a return to confident arrogance, of which resisting new capital ratios are shots across the bows of the regulators?
The threats are poor thanks for Government and Bank of England’s heroic roles as lenders of last resort in baling underwater banks. All banks were helped by state aid packages. Banks that did not require direct aid, or not as much as others, yet benefited massively from the help given to others. When Lehman Brothers collapsed, for example, among a host of emergency measures there was $2.5 trillion alone in temporary liquidity by the Fed, BoE and ECB to resolve failed money market trades.
Dame Angela (for the BBA) wants the new rules carefully handled to avoid “prolonging the downturn”. The banks got eight years, a long time in banking. She says, “The consequence is that inevitably the cost of credit – the price the borrower pays for money – will rise. The cheap money era is over.” Surely, a fun remark when the central bank rates continue negative in real terms. A lobbyist for bankers, the IIF used similarly dramatic language to persuade the Basel committee to dilute its reforms. Do bankers think we, politicians and taxpayers, learned nothing about how banks operate, or about how blinkered, self-serving, solipsic and short-termist their thinking can be?
The job of bank risk regulators can seem like herding cats!
The WSJ’s David Weidner wrote: “Judging by their hokey scare tactics, you'd think the act of raising capital requirements during an eight-year span was the final blow to capitalism. But it's not. Basel III is a compromise tilted toward an international banking community that's woefully undercapitalized and vulnerable to breakdowns.”
In truth, banks have far flexibility and head-room than their lobbyists want us to see. The public was not fond of banks before the crisis and now views them with mistrust, hatred, and derision. What other industry can prosper when so unpopular?
Banks do not have to make their customers pay; bankers can reduce their own bonus levels for a start, or perhaps regulators should do so – they now have that power! Banks’ pretence that certain people will only work for guaranteed bonuses, as for example for managers of ‘prime services’ to lend to hedge funds. Remarkably, it is so hard to lend them money this requires $5m guranteed bonuses?
Saving losses, what risk managers do, is never so generously incentivized, not remotely so? It is like paying football midfielders thirty times what the goalie gets, and strikers and team manager fifty times as much!
Privately, bankers, regulators, and most everyone else know that “incentivising” star players by handing them bonuses in excess of either group profit or loss damages credibility, solvency and shareholders. Fiduciary prudence is replaced by something else, poorly understood or defined except to call it ‘daylight bank robbery’ or ‘greed’. That is the dominant political and general voting public’s view. Are they wrong?
As someone who enjoys a spendthrift life on high-fees, I understand that heady culture that I am also part of, if better looking than Dick Fuld and freer than Bernie Madoff. Ah sure, wouldn’t we all be somewhat poorer for not having outrageously super-rich like us to gawk at, demonize and blame – but not if the consequence are distorted values that risk our whole economy! Martin Wolf in the FT wrote, “withdrawing incentives for reckless behaviour is not a cost to society; it is costly to the beneficiaries. The latter must not be confused with the former.”
Banks may reduce the capital they have committed to proprietary trading, to speculation, to profit from markets beyond lending to them. Banks may cash in realizable profits and sell non-core assets. Over the years banks can generate internal capital without upping borrowing costs of households and small firms. UK banks would do well to lend more to small firms who employ 40% of all jobs but only get 1.5% of non-financial loans – in the USA 10% and in Germany 19%. Banks can tap equity and bond markets for capital and retain more of net earnings before bonuses. When will they tell shareholders how much bonus is performance related or guaranteed?
The lobbying by IIF used the difficulties of Europe’s local savings banks such as in Germany and Spain, resulted in all banks getting a suspiciously long time to build new reserves, from 2013 to 2019. By then, all current top execs will have retired, rich, and we’ll be in the next recession when government again has to reflate the economy without help from banks!
Rather than scaremongering, bankers should grow up and recognise their priority is to rebuild moral authority and trust by customers, taxpayers and others, not least shareholders, show willingness to adapt their business models and pay themselves less. Scare-mongering fools no-one except the gullible of whom there are precious few left for banks to rely on for support today?
The banking lobbyists’ churlish failure to apologize or acknowledge that they must mend their ways and change how they do business and what is realistic and reasonable risk-based profit only does more damage to the recovery, not of the economy only, but that banks need to make to recover customer and taxpayer trust and loyalty, real self-belief and fiduciary responsibility, including in macro-prudential terms, i.e. real banking professionalism – or maybe I’m just old-fashioned, a grumpy old banker well past my sell-by-date?
______________________________________________
*Note: Ingrate, n. One who receives a benefit from another, or is otherwise an object of charity -Devil’s Dictionary.
**Note: Reminding us of, from “The madness of Crowds”, about the inventor of modern bonds, John Law, “he understood the monetary question better than any man of his day; and if his system fell with a crash so tremendous, it was not so much his fault as that of the people amongst whom he had erected it. He did not calculate upon the avaricious frenzy of a whole nation; he did not see that confidence, like mistrust, could be increased almost ad infinitum, and that hope was as extravagant as fear. How was he to foretell that the French people, like the man in the fable who killed in frantic eagerness the fine goose he bought to lay golden eggs?” (Charles Mackay writing in 1841)

Wednesday, September 1, 2010

MOODY'S BUGS CLEARED ON A TECHNICALITY

Moody’s has avoided prosecution by SEC and others on a technicality, announced some three years after the SEC investigation began!
Sam Jones, wrote in FT’s Alphaville over two years ago about bugs in Moody’s model for rating securitization issues that mistakenly gave top ratings for bonds.
When re-rated after June 2007 using a model in which the bugs had been fixed tens of $billions of CDOS, RMBS, ABS bonds dropped in value by up to 17 risk grades, sometimes from Aaa straight to 'Junk'! Moody's between 2005 and 2007 risk rated about 10,000 Residential Mortgage Backed Securities (RMBS).
http://ftalphaville.ft.com/blog/2008/05/21/13198/ft-alphaville-exclusive-moodys-error-gavetopratings-todebtproducts/
This was based on a fuller account that appeared in a few blogs including my own. Moody’s awarded incorrect triple A ratings to tens of billions of dollars worth of a type of asset covered bonds. The FT wrote, “Internal Moody’s documents seen by the FT show that some senior staff within the credit agency knew early in 2007 that products rated the previous year had received top-notch triple A ratings and that, after a computer coding error was corrected, their ratings should have been up to four notches lower…” In 2007 moody's downgraded about one third of all RMBS. This was the mild form of the story.
It was not just about ratings in 2006; between 2000 and 2007, Moody's rated $4.7 trillion in RMBS! For some model descriptions: Moody’s used its Moody's Individual Loans Analysis (MILAN) model for collateral analysis with a cash flow model such as Moody’s Analyser of Residential Cash Flows (MARCO) or ABSROM. Moody’s analysis was intended to provide RMBS investors with a consistent and transparent system of gradation by which relative credit quality is expressed.
The lack of transparency issue has however been the leading criticism by regulators. The Moody’s objective was laudable - to assign the same ratings to all debt instruments exposed to equivalent credit risks over time, irrespective of the country of origin, the industry sector or the structure of the security. This aim is however subject to differences in law regarding the underlying rights of mortgage borrowers and how the property collateral may be recovered.
Moody's aim was that over the same period of time, portfolios of structured finance securities with the same ratings should sustain similar credit losses. But, the problem remained of not just the history of defaults in the models (or not if they failed to be updated and when the models appeared indifferent to default rates) but also the forecasting of defaults under various economic scenarios?What happened was that Moody’s modelers noted a speech by Ben Bernanke in January 2007 where he reported that default rates were below 2%, which seemed both counter-intuitive and contrary to other earlier reported figures of 4% and rising. Bernanke had taken his data from Freddy Mac and Fanny Mae, data that was actually post-adjustment after many mortgage deals had been restructured. The modelers decided to put progressively higher default data into their models only to find that every time they cranked the numbers the result was always triple-A or otherwise unchanged from before i.e. the bugs in the model meant they were indifferent to default rates – seriously flawed fundamental errors! And, then they discovered that the models in any case had not been updated for default rates for some years!
When Moody's announced on June 5, 2007 that it was introducing changes to its model, it did not reveal how fundamental this was. It said "Moody's Expands Loan Characteristics in Subprime RMBS Ratings Analysis - New York, June 05, 2007 -- Moody's Investors Service announced today that its analysis of securities backed
by pools of sub-prime residential mortgages closing after July 1, 2007 will be expanded to include a systematic assessment of certain variables described in the Special Report, "Moody's Revised US Mortgage Loan-by-Loan Data Fields," published April 3, 2007. In addition, Moody's will be modifying the way it incorporates some other factors into its analysis. The refinement of its rating methodology is part of Moody's continuing effort to incorporate the expanding range of loan and borrower characteristics now being captured by many mortgage originators as well as the
performance data that has been accumulated during the past few years in the rapidly growing and evolving sub-prime mortgage market. Moody's expects to continue to refine its methodology in the future as it continues to analyze the increasing amount of performance information that becomes available.
"
This made the changes seem merely benign, when in fact they heralded the bottom falling out of the interbank credit market. To those who need to know a little of the technicalities, it may be of interest to note that given limited historical data, Moody’s used three parameters to determine the "lognormal loss distribution": − expected loss (base case losses) of the portfolio − adjusted MILAN Credit Enhancement, and − average life of the portfolio.
Moody’s assessed the expected loss using historical default and recovery data "provided by the Originator" or "based on comparable portfolios and benchmarking". All very well, but range of possible loss data is surely the main feature that the ratings agency model should be bringing to the analysis, not merely using the issuer's own data?Moody’s used MILAN to determine the MILAN Credit Enhancement (CE), and, in order to derive the ratings of the Notes, Moody’s used a cash flow model, MARCO, which included "key structural elements". MILAN was a risk scoring model, which is not ideal; each loan compared and scored against a country-specific benchmark loan, then, based on certain assumptions (mainly loan to value ratios that are especially relevant in the US, but much less so elsewhere). The credit enhancement necessary to agree with the benchmark loan can be determined, then tagged to a specific rating level (somewhat circular). No mention is made in the Moody's literature I have seen of credit cycle or economic cycle or macro-economics at all!
Overriding accuracy issues for the ratings agencies was also competitive ones of how to win ratings of big issues when the issuers could shop around for who would produce milder or harsher ratings! The question remains unanswered as to whether the ratings models of Fitch and S&P were a lot better than Moody’s or not?
Several internal emails have come to light that show this. For example, a July, 2004 S&P email: "We are meeting with your group this week to discuss adjusting criteria for rating CDOs of real estate assets this week because of the ongoing threat of losing deals. . . ." [emphasis in original] A March, 2005 S&P email chain shows that agency was slow to roll out ratings model changes because the updated model produced harsher results. Parts of the chain: "When we first reviewed [model] 6.0 results **a year ago** we saw the sub-prime and Alt-A numbers going up and that was a major point of contention which led to all the model tweaking we've done since. Version 6.0 could've been released months ago and resources assigned elsewhere if we didn't have to massage the sub-prime and Alt-A numbers to preserve market share."
Emails at Moody's include in May, 2007: "Thanks again for your help (and Mark's) in getting Morgan Stanley up-to-speed with your new methodology. As we discussed last Friday, please find below a list of transactions with which Morgan Stanley is significantly engaged already. . . . We appreciate your willingness to grandfather these transactions [with regards to] Moody's old methodology." And also in August, 2007 Moody's email: "[E]ach of our current deals is in crisis mode. This is compounded by the fact that we have introduced new criteria for ABS [asset-backed securities] CDOs. Our changes are a response to the fact that we are already putting deals closed in the spring on watch for downgrade. This is unacceptable and we cannot rate the new deals in the same away [sic] we have done before. . . . bankers are under enormous pressure to turn their warehouses into CDO notes."
Such emails show considerable overlap between quality of models and competition for the business to the extent that could be deemed evidence of compromising fiduciary duty to investors etc.
See DailyFinance: http://www.dailyfinance.com/story/investing/more-hot-emails-put-new-heat-on-the-credit-rating-agencies/19452156/?icid=sphere_copyright
Moody's had several points in its modeling where results could be massaged. There was comparison of the specific loan, property and borrower characteristics underlying each loan with those of the benchmark loan. This, if fully true, must have involved massive computing, which I sense may not have been fully deployed.
This then leads to adjustments to necessary credit enhancements of each loan, which are then compared to the minimum credit enhancement determined for a country. Again, we may wonder at the resilience of the benchmark concept?
Once each loan was scored, the portfolio was compared with the country benchmark RMBS in terms of regional, borrower and loan concentrations. This led to additional adjustments on the credit enhancement and ultimately produced the MILAN Credit Enhancement for the portfolio, relating to a specific rating level.
All steps are analysed and discussed by a rating committee. After, and if, further quantitative and qualitative adjustments to the MILAN CE by the rating committee (resulting in the adjusted MILAN CE), then, given a lognormal loss distribution, MARCO is used as a cash flow model for how different features in the transaction impact the final ratings of the Notes (each of the tranches of the securitised bond issued by the SIV).
The model calculates the loss and the average life of the Notes resulting from each portfolio loss scenario of the lognormal curve. The model will then weight each loss and average life on the Notes with the corresponding probability of the loss scenario.
The result is the expected loss and the weighted average life for each tranche in the capital structure. With these two inputs, the ratings can be derived from Moody’s Idealised Expected Loss Table.
That sounds simple actually, simply a way of getting the securities to comply with a standard ratings table. That is, until it is discovered in January 2007 that the models did not actually respond to different default or expected loss rates and that loss rates, presumably for the benchmark loans, had not been updated for several years before 2007!
Former Moody’s Executive Brian Clarkson described the approach as “you start with a rating and build a deal around a rating”.
While it certainly does exist, rating shopping appears to be a more significant issue in single-issuer debt ratings than in structured ratings. Given that single issuers exist prior to their rating and it is more difficult to change their existing businesses, balance sheets, income statements or structures in anticipation of review, rating shopping is a justified concern.
In structured securities, the SIV corporation (trust) does not exist prior to the rating, the structure to be achieved in order to garner a desired rating is defined by the rating agencies. As a result rating shopping is less a concern than is the pre-rating back and forth negotiations and substitution of underlying collateral which allows issuers to work with the rating agency until they create the structure that achieves the desired rating.
Working backwards and using feedback adjustments to get to a desired ratings is one thing, but operating models that are indifferent to default rates is another. Moody's modelers in January 2007 fixed these latter calamitously major bugs in the models and then found that the bonds or notes when reprocessed dropped by up to 17 risk grades! This they reported upstairs to a shocked board, who must have seen instantly that their company was now at major risk, and perhaps they might have also seen that the whole banking market was also at major risk.
The modelers were told to unfix the fixes and sit on this until it was decided how to handle this; how to tell the world? That thought-leadership process took 6 months, during which time other mind-focusing events occurred such as Bear Stearns securitisation collateral seized and sold at fire-sale prices by Citicorp's back office, triggering Bear's eventual collapse and US Treasury assisted fire-sale to JP Morgan Chase, and then UBS and Citicorp's own structured products exposures were subject to large writedown losses!
Yet, Moody's did not publicly mea culpa or publicly revamp its model until mid-year.
It made an announcement of a new model in June 2007. The news was not considered of fundamental importance to any but perhaps a few.
Then, from June 2007, using a newly fixed model. Moody's regraded securitization issues, mainly RMBS (of which Moody’s had graded more than half of all issues, or $4.7 trillions), that when cranked through the valuation model (a process like Chinese water torture on the interbank credit markets) with day after day, week after week, bank-issued (via SIVs) asset backed bonds and SIV notes (tranches) being severely downgraded that forced banks and eventually other investors to announce major writedown losses! For example on just one perhaps typical day, Moody's Credit Research Announcement 10 JUL 2007 "Moody's downgrades 399 subprime RMBS issued in 2006; 32 additional securities placed on review for possible downgrade". $ billions of RMBS were being downgraded every day.
Confidence in banks’ securities progressively collapsed and the Credit Crunch wreaked havoc on banks’ share values as well as on their ability to finance their funding gaps.
An SEC investigation followed the FT’s exclusive, EU authorities too, not least DG McCreevy when head of Ecofin, were extremely angry at the damage caused and considered suing the ratings agencies in court. Reforming credit ratings agencies became an important part of the G20 agenda. In various parts of the world including Europe various measures were considered and are being introduced to reduce reliance of the US credit ratings agencies. But, this is very difficult to do! It was obvious that when the ratings were re-run by Moody’s through new models in the second half of 2007, every week more downgrades, that coincided with full onset of the Credit Crunch.
It is reasonable to ask therefore if the securitization issues been properly, accurately, assessed, could the worst of the Credit crunch have been avoided? That is a big question, a big issue!
Similar criticisms of the ratings agencies followed in the wake of the Enron scandal but SEC legal action was not followed through with and was dropped. Enron's rating remained at investment grade until four days before the company collapsed. Similar failures were repeated in the cases of Bear Stearns and Lehman Brothers, and other firms. The ratings agencies failed in the case of Enron to notice that financial trusts linked to Enron made financial commitments largely based on Enron’s share price!
There were regulatory reforms in the US credit rating industry, the Credit Rating Agency Reform Act of 2006, and that put them in the context of the Sarbanes–Oxley Act of 2002. The SEC committed to improve the quality and integrity of the credit rating industry, but instead of focusing on detail resorted to broad reforms such as increasing competition between credit rating agencies including through new market entrants. That the SEC has in the case of Moody’s dropped further investigation on a technicality may have something to do with its own culpability. The SEC has been equipped with enforcement measures, which include the suspension and revocation of NRSRO status, and that may be used, for example, when a credit rating agency does not comply with procedures regarding the prevention of the misuse of material non-public information, conflicts of interest, and other abusive practices. Credit rating agencies are subject to (onsite) examination by SEC and extensive documentation retention and management programmes. It will be a long time before new competition can have a desired effect of improving the quality and integrity of the global US credit rating firms (the big three).
Arguably, the credit rating agencies are more powerful than the regulators in determining the creditworthiness of banks and their bonds. They also have a major responsibility and impact influence on sovereign ratings of governments. Given the influence of credit rating agencies in the capital markets and their regulatory responsibility as private-sector watchdogs, increased oversight of the credit rating industry is most laudable, but also most intimidating for regulators however backed by governments to undertake. Credit rating agencies currently remain prominently in the spotlight of national, federal, and international securities regulators, but appear let off the hook by the SEC, but only on a technicality. They remain subject to possible other agencies including private class actions slowly moving through the courts such as by CALPERS http://online.wsj.com/public/resources/documents/calpers.pdf
Three years on, on Tuesday, 31 August 2010, the SEC released this: “The Securities and Exchange Commission today issued a report cautioning credit rating agencies about deceptive ratings conduct and the importance of sufficient internal controls over the policies, procedures, and methodologies the firms use to determine credit ratings.”
The FT commented that the SEC’s Report of Investigation stems from an Enforcement Division inquiry into whether Moody’s Investors Service, Inc. (MIS) — the credit rating business segment of Moody’s Corporation — violated the registration provisions or the antifraud provisions of the federal securities laws. The Report says that “because of uncertainty regarding a jurisdictional nexus between the United States and the relevant ratings conduct, the Commission declined to pursue a fraud enforcement action in this matter…”
So, Moody’s has escaped prosecution for “fraud” because the relevant American legislation was defective – a shortcoming, the SEC notes has been expressly addressed in the newly-minted Dodd-Frank Wall Street Reform and Consumer Protection Act.
You can read the report at http://www.sec.gov/litigation/investreport/34-62802.htm
On May 20, 2008, the Financial Times published on its Web site an article that disclosed the coding error, citing internal Moody’s documents that showed the error had been discovered by MIS over a year earlier, and alleged that MIS had incorrectly awarded Aaa credit ratings to CPDO notes because of the error.
When Moody’s was contacted by reporters gathering information for the story, the company began an internal investigation into the coding error and the CPDO rating committee conduct. On July 1, 2008, a year and a half after the coding error had been discovered, and over a year after the European rating committee had declined to downgrade the credit ratings, Moody’s issued a press release discussing the investigation results and stating that “some committee members considered factors inappropriate to the rating process when reviewing CPDO ratings following the discovery of the model error.” Thereafter, MIS took personnel action with respect to management of the CPDO group and members of the committee, including termination of the Group Managing Director and two Team Managing Directors…
…Further, we conclude that, in early 2007, members of the European rating committee believed they could violate MIS’s procedures without detection, and in fact the conduct did not come to light until the Financial Times contacted MIS about the error in the CPDO model and an investigation ensued…
Note that today Moody's re-ratings actions based on improving or continued deterioration of subprime securitisations, or in conjunction with distressed or improving house price and rising or falling unemployment, will run each individual pool of mortgage loans through a number of stress scenarios to assess the rating implications of updated loss expectations. The scenarios include 96 different combinations within six loss levels, four timing curves and four prepayment curves.
For much more on all of this, I wrote about it in October 2008
http://bankingeconomics.blogspot.com/2008/10/risk-rating-smoking-gun.html
Also see:
http://newsroom-magazine.com/2010/governance/financial-crisis-governance/moodys-internal-corruption-detailed/
http://www.fcic.gov/reports/pdfs/2010-0602-Credit-Ratings.pdf